Closing a paid-off credit card can feel like responsible financial housekeeping, but it is one of the most common credit score mistakes. Scoring formulas reward longevity and available credit, so shutting an account, even one you rarely use, can signal increased risk to the bureaus.
1. Lowering Total Available Credit
Your score depends heavily on how much of your available credit you use. Closing a card instantly shrinks your total pool. If you hold two cards with $5,000 limits each and close one, your available credit drops from $10,000 to $5,000 overnight.
2. Spiking Utilization Ratio
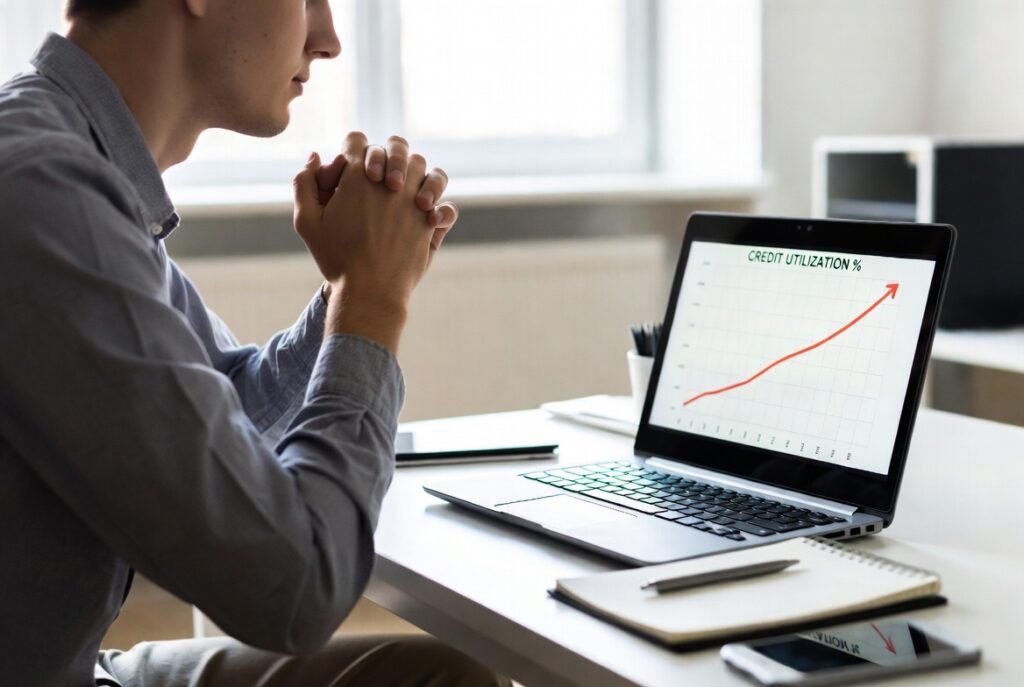
Credit utilization is the share of your limit currently owed. A $2,000 balance against a $10,000 limit is 20 percent utilization, but close a card and that same $2,000 against a $4,000 limit jumps to 50 percent. Experts recommend keeping utilization below 30 percent.
3. Shortening Your Credit History
Lenders favor borrowers with long track records of managing debt. Your score factors in the average age of all accounts, so closing a card you have held for a decade or more drags that average down and makes your history look younger.
4. Losing a Long-Standing Positive Record
Old cards kept open for years anchor your credit report with proof of a stable lender relationship. Closing one erases that evidence of reliability from your active profile.
5. Weakening Your Credit Mix
Bureaus like to see variety: credit cards, auto loans, mortgages. If the card you close is one of your few revolving accounts, your mix becomes less diverse, which can cost you a few points.
6. The Ten-Year Falloff Rule
A closed account in good standing stays on your report for about ten years, continuing to support your average account age. When it finally falls off, your average age can drop sharply, with a bigger impact than many expect.
7. Potential for Quick Point Loss
Scores are recalculated as new data is reported, so losing a credit limit can trigger an immediate drop of several points. That timing hurts most when you are about to apply for a mortgage and need every point.
8. Closures That Signal Distress
Closing several accounts in a short period can make lenders wonder whether you are struggling with hidden debt. Stable, long-held accounts signal sound finances, while frequent changes create a noisy report that worries underwriters.
9. Hidden Value of Inactive Accounts
Even a dormant card with no balance quietly helps your score by padding your total available credit. As long as it carries no steep annual fee, keeping it in a drawer lets it age and support your utilization ratio at zero cost.
10. Losing Proof of “Good Debt” Management
Not all debt is bad. An open card with a zero balance demonstrates that you can hold credit without misusing it. Closing that account removes visible proof of your discipline from your active file.
