Americans have fundamentally changed how they manage money over the past few years. Traditional banking habits are giving way to technology-driven strategies, as economic pressures and new attitudes toward financial success reshape everyday decisions.
1. The Rise of AI Financial Partners
Artificial intelligence has moved from novelty to everyday financial assistant. Modern apps now forecast monthly spending, cancel unused subscriptions, and automatically move spare cash into high-yield savings accounts. What once required hours of manual budgeting now happens quietly in the background.
2. The Mindful Spending Conflict
Consumers are caught between two extremes: impulse buying and aggressive saving. Rising prices have forced cutbacks on essentials, yet many deliberately budget for small treats that bring joy. The new discipline is intentional spending aligned with personal priorities.
3. Credit Card Skepticism and the BNPL Boom
Younger Americans increasingly distrust credit cards, viewing high interest rates as a debt trap. Buy Now, Pay Later (BNPL) services have surged as a result, with installment plans perceived as a more transparent way to manage large purchases without revolving debt.
4. The Era of Financial Realism
The “get rich quick” mindset has given way to financial realism. Priorities now include eliminating high-interest debt, building emergency funds capable of weathering shutdowns or downturns, and ensuring income growth outpaces inflation.
5. High-Yield “Cash Stashing”
For the first time in over a decade, cash earns meaningful interest. Savers are hunting for the best high-yield savings account and certificate of deposit (CD) rates, moving money out of big-bank checking accounts paying near zero into digital banks offering far better returns.
6. The “Bifurcated” Consumer Strategy
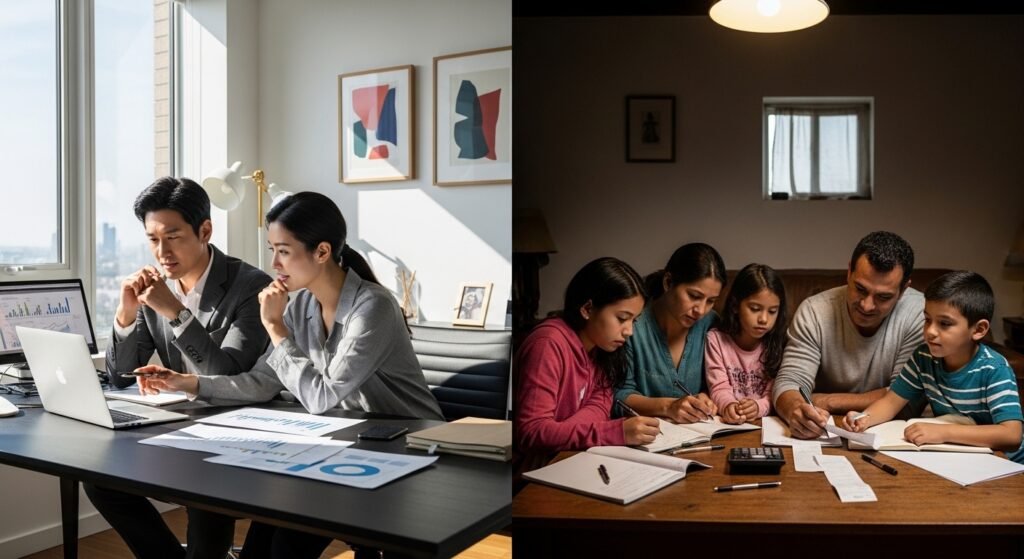
A widening gap separates how income groups spend. Higher earners pursue stealth wealth and private-market investments, while middle- and lower-income households practice financial gymnastics: frugal weekdays funding social spending and travel on weekends.
7. The Death of the Physical Branch
Opening a bank account from the couch is now the norm. Banks win new deposits by removing digital friction, and consumers expect apps that work around the clock and integrate seamlessly with Apple Pay, Venmo, and other payment systems.
8. Value-Based and Ethical Investing
More investors align portfolios with personal values, screening for environmental commitments or diversity standards. Where money is parked has become a form of social voting, with capital flowing away from brands that fail ethical tests.
9. The “Side Hustle” as a Requirement
A 9-to-5 salary alone no longer feels sufficient. Gig work, freelancing, and digital products have become standard second income streams, providing a financial safety net and resilience against job market uncertainty.
10. Hyper-Personalization in Wealth Management
The one-size-fits-all portfolio is obsolete. New tools let even small investors customize strategies around life goals, tax-loss harvesting, and themes like artificial intelligence or green energy. Personalization is now the baseline expectation, not a premium perk.
