Building an emergency fund is one of the most important financial moves you will ever make. It is not just about protection. It buys peace of mind when the car breaks down or a job disappears. In an era of rising costs and unpredictable markets, a safety net is your fundamental defense against financial stress.
1. Focus on the “Starter” Goal First
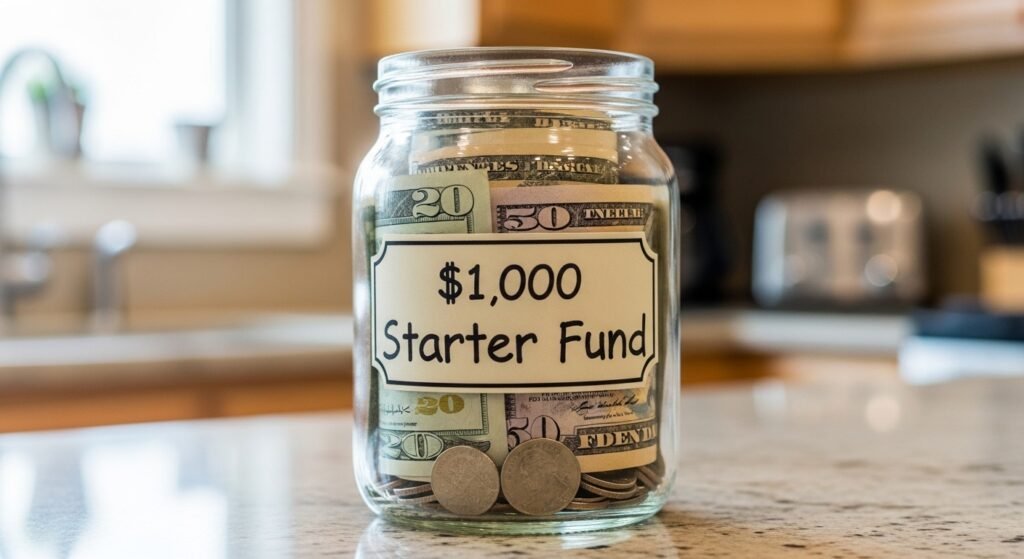
A full emergency fund feels overwhelming, so start with a starter goal of $1,000 to $2,000. That modest cushion covers the vast majority of common household emergencies and keeps you from reaching for a credit card.
2. Use the 3-to-6 Month Rule
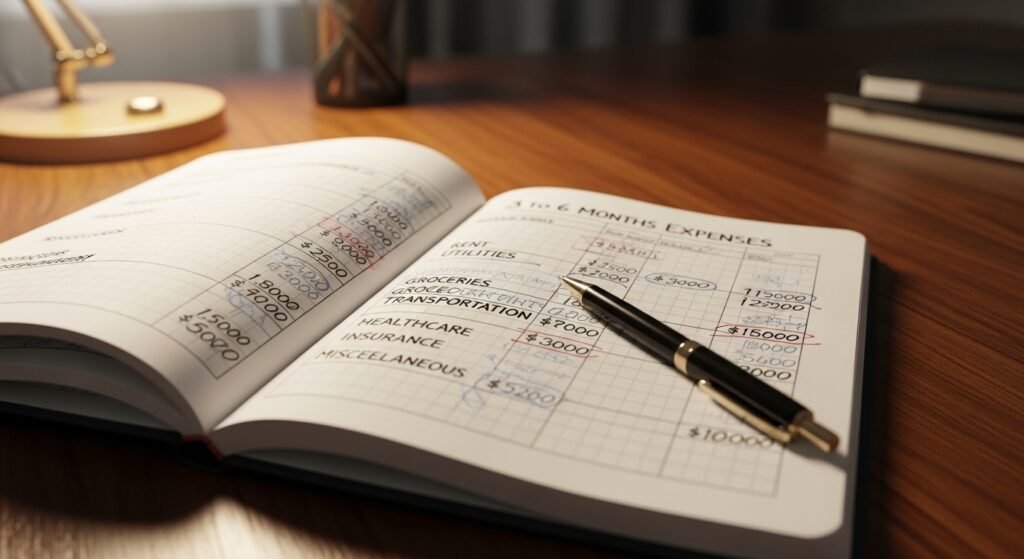
Your complete fund should cover three to six months of essential living expenses. Three months may be enough if your job is stable and you have no dependents. Aim for six months if you are self-employed or support a family.
3. Prioritize Liquidity Over Growth
An emergency fund is insurance, not an investment. Do not put it in the stock market chasing returns. If you lose your job during a market crash, your safety net could vanish at the worst moment. Keep it in a secure, easily accessible account.
4. Automate the Process
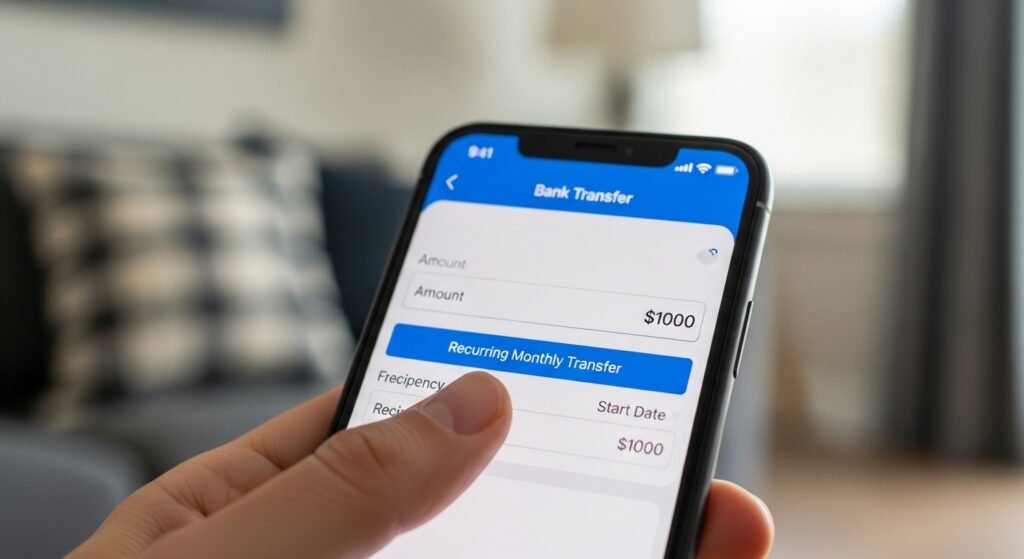
The best way to save is to make it invisible. Set up automatic monthly transfers from your paycheck or checking account into your emergency fund. Treating savings as a required expense means your fund grows even when you are not thinking about it.
5. Save Your “Windfalls”
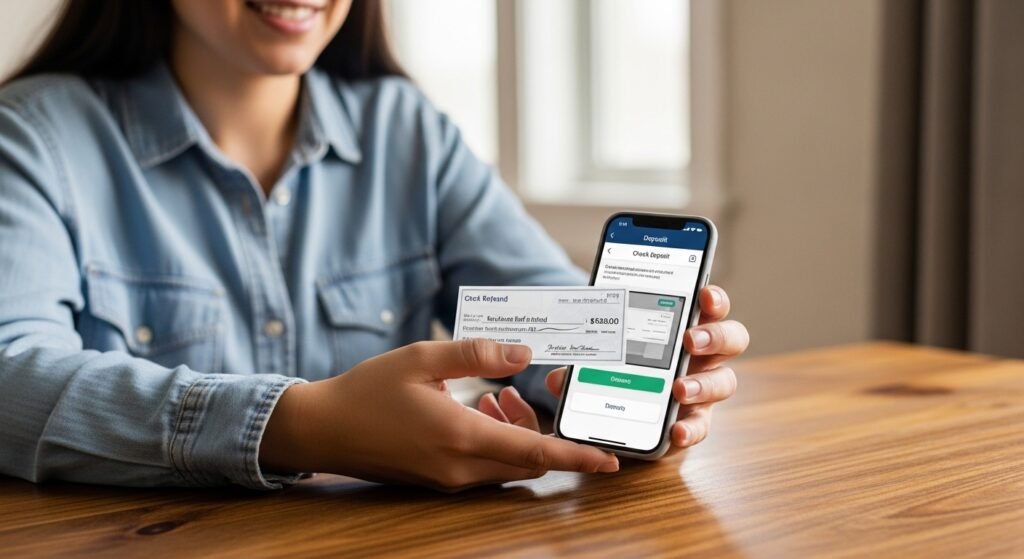
Direct most of your unexpected income, such as tax refunds, work bonuses, and cash gifts, straight into your emergency fund. Windfalls accelerate your progress without forcing you to cut monthly spending.
6. Define a “True” Emergency
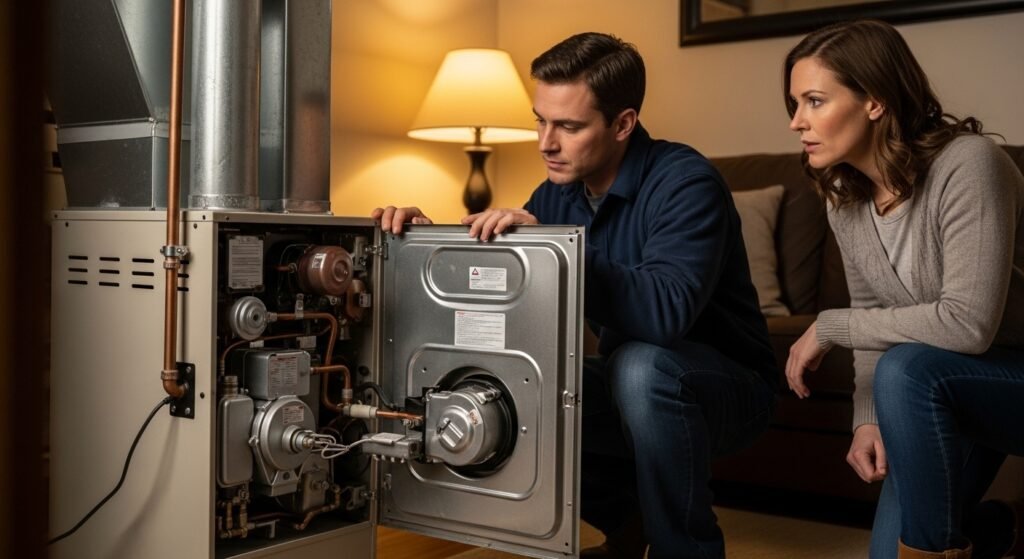
Set strict rules for when you can touch the fund. A true emergency is sudden and urgent: a broken furnace in winter qualifies, a television sale does not. Anything you can plan and save for separately is not an emergency.
7. Replenish Immediately
Refill the fund as soon as you dip into it. Restore your safety net to its full level before redirecting extra money elsewhere. An empty emergency fund leaves you exposed to the next crisis.
8. Factor in High Insurance Deductibles
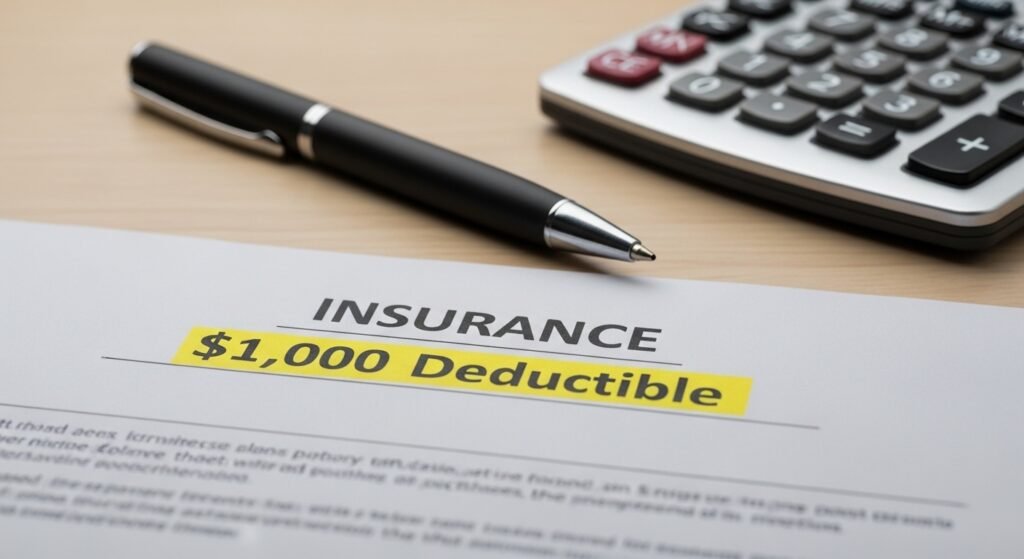
Check the deductibles on your health, auto, and home insurance. Your emergency fund should at least cover those amounts. If your car insurance has a $1,000 deductible, your fund must bridge that gap before coverage kicks in.
9. Avoid the “All or Nothing” Mindset
Many people never start because they cannot save a large amount at once. Saving $20 a week beats saving nothing every time. A small fund that grows slowly still protects you better than no fund at all. Start where you are and increase contributions as your income rises.
10. Review the Total Annually
Your fund should evolve with your life. Moving to a pricier city, having a child, or taking on a new loan all raise your monthly essentials. Review your safety net once a year to confirm it still covers your needs.
